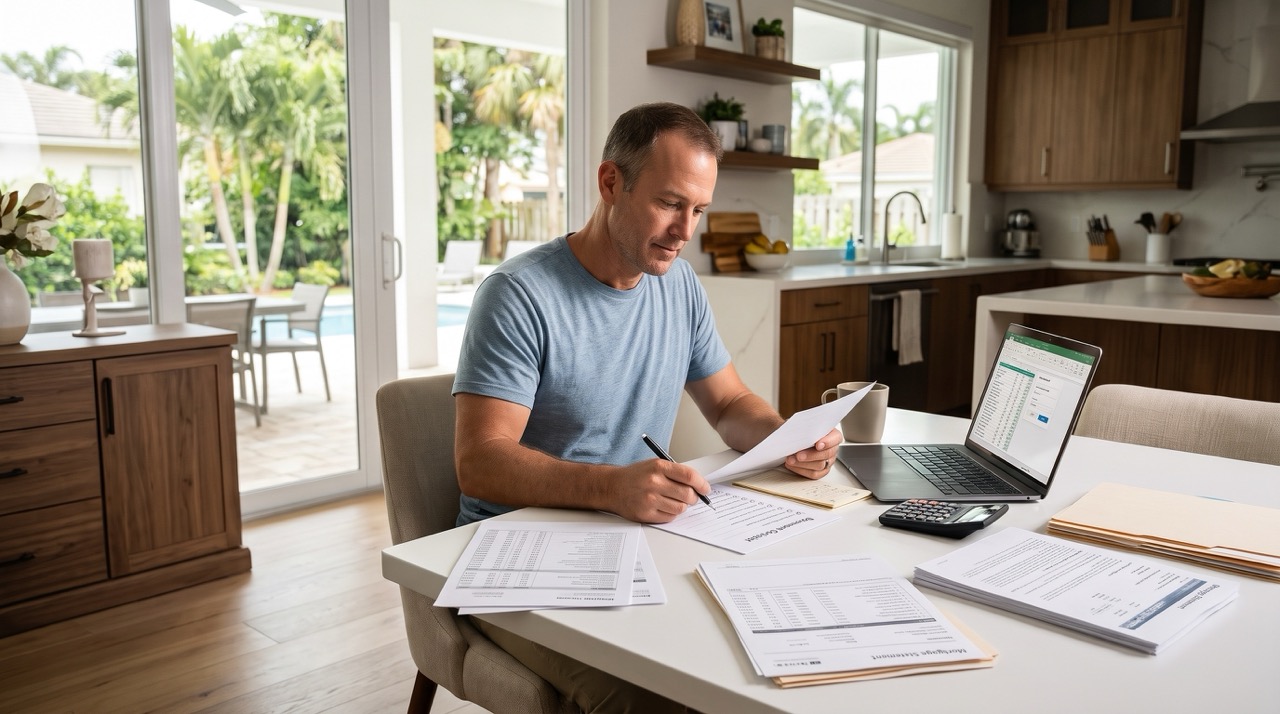
 Team Hinman, led by residential mortgage specialist Jamie Hinman (NMLS #1074223), has published a new article on its blog that outlines the documents lenders typically request when homeowners apply for a home equity line of credit (HELOC). The article presents the information as a checklist intended to help applicants assemble their paperwork before a file reaches underwriting.
The checklist organizes common lender requests into five categories: income and employment, assets, property, credit and liabilities, and identity. The article also explains why documents matter to an underwriter, which federal disclosures borrowers are entitled to receive, and how to organize records for submission.
A HELOC is a revolving line of credit secured by the borrower’s home. Lenders generally evaluate an applicant’s ability to repay, available home equity, existing debts and credit history. Depending on the lender and program, that review may include debt-to-income and combined loan-to-value calculations. Missing documents can prevent an underwriter from completing parts of the review and may delay approval.
Team Hinman's checklist encourages homeowners to gather complete, current records early. Missing pages and outdated statements can lead to follow-up requests, while preparing documents in advance can help applicants respond when a lender asks for additional information.
For salaried and hourly applicants, lenders may request recent pay stubs, often covering 30 days, and W-2 forms for the past two years. Self-employed applicants may be asked for personal tax returns, applicable business tax returns, a current profit-and-loss statement and business bank statements. Required records, documentation periods and business ownership thresholds vary by lender and program.
Lenders may also ask applicants to sign IRS Form 4506-C to authorize an approved Income Verification Express Service participant to obtain IRS tax transcripts for income verification.
On the asset side, the checklist advises applicants to confirm which accounts require documentation and provide complete statements for the periods requested, including all pages when required by the lender. A lender may request an explanation and supporting records for unusual deposits when their source is relevant to income or asset verification.
Property records make up another section of the checklist. Depending on the property and lender, applicants may be asked for the declarations page from their homeowners insurance policy, property tax records and applicable flood or windstorm coverage documentation. Condominium applicants should ask whether association contact information, current dues and master insurance records are required.
The residential mortgage specialist also shared lenders’ disclosure obligations. For HELOCs covered by the Truth in Lending Act and Regulation Z, creditors generally must provide required disclosures about fees, payment terms and any variable-rate features when the application is provided, along with the Consumer Financial Protection Bureau’s HELOC booklet or a suitable substitute. Timing exceptions apply to certain application channels.
For a covered HELOC secured by the consumer’s principal dwelling, the right to cancel generally lasts until midnight of the third business day after account opening or delivery of the required rescission notice and material disclosures, whichever occurs last. Cancellation must generally be made in writing.
The article distinguishes between the records applicants provide for underwriting and the disclosures creditors provide to explain a HELOC’s terms. It encourages applicants to review those disclosures and ask questions about rates, fees, payment requirements and cancellation rights.
The HELOC approval checklist blog closes with practical advice on organizing an application package. It recommends following the lender’s submission instructions, using its approved secure upload method and providing complete, legible files. Where accepted by the lender, applicants can submit PDFs and combine multi-page statements into single files.
Applicants should begin gathering records early because preparation time varies. Lenders may request updated statements or clarification when names, employment information or other application details do not match. Document-age requirements vary by lender and program.
For more information, visit Team Hinman's website at www.teamhinman.com.
About Team Hinman
Team Hinman is led by Jamie Hinman, a residential mortgage specialist (NMLS #1074223). The team works with homeowners, self-employed borrowers and real estate investors on home financing options, including home equity lines of credit, refinancing, purchase loans and reverse mortgages. Team Hinman operates from its office at 9655 S Dixie Hwy, Suite 200, Pinecrest, FL 33156, and can be reached at (786) 208-6293.
Jamie Hinman (NMLS #1074223) of Team Hinman. Equal Housing Opportunity. Loan programs, terms, and availability are subject to change and borrower qualification. This content is for informational purposes and does not constitute a commitment to lend.
###
For more information about Team Hinman, contact the company here:
Team Hinman
Jamie Hinman
(786) 2086293
jamie@teamhinman.com
1701 Ponce de Leon Blvd 4th Floor, Coral Gables, FL 33134, United States (but we have transferred to 9655 S Dixie Hwy Suite 200 Pinecrest, FL 33156)